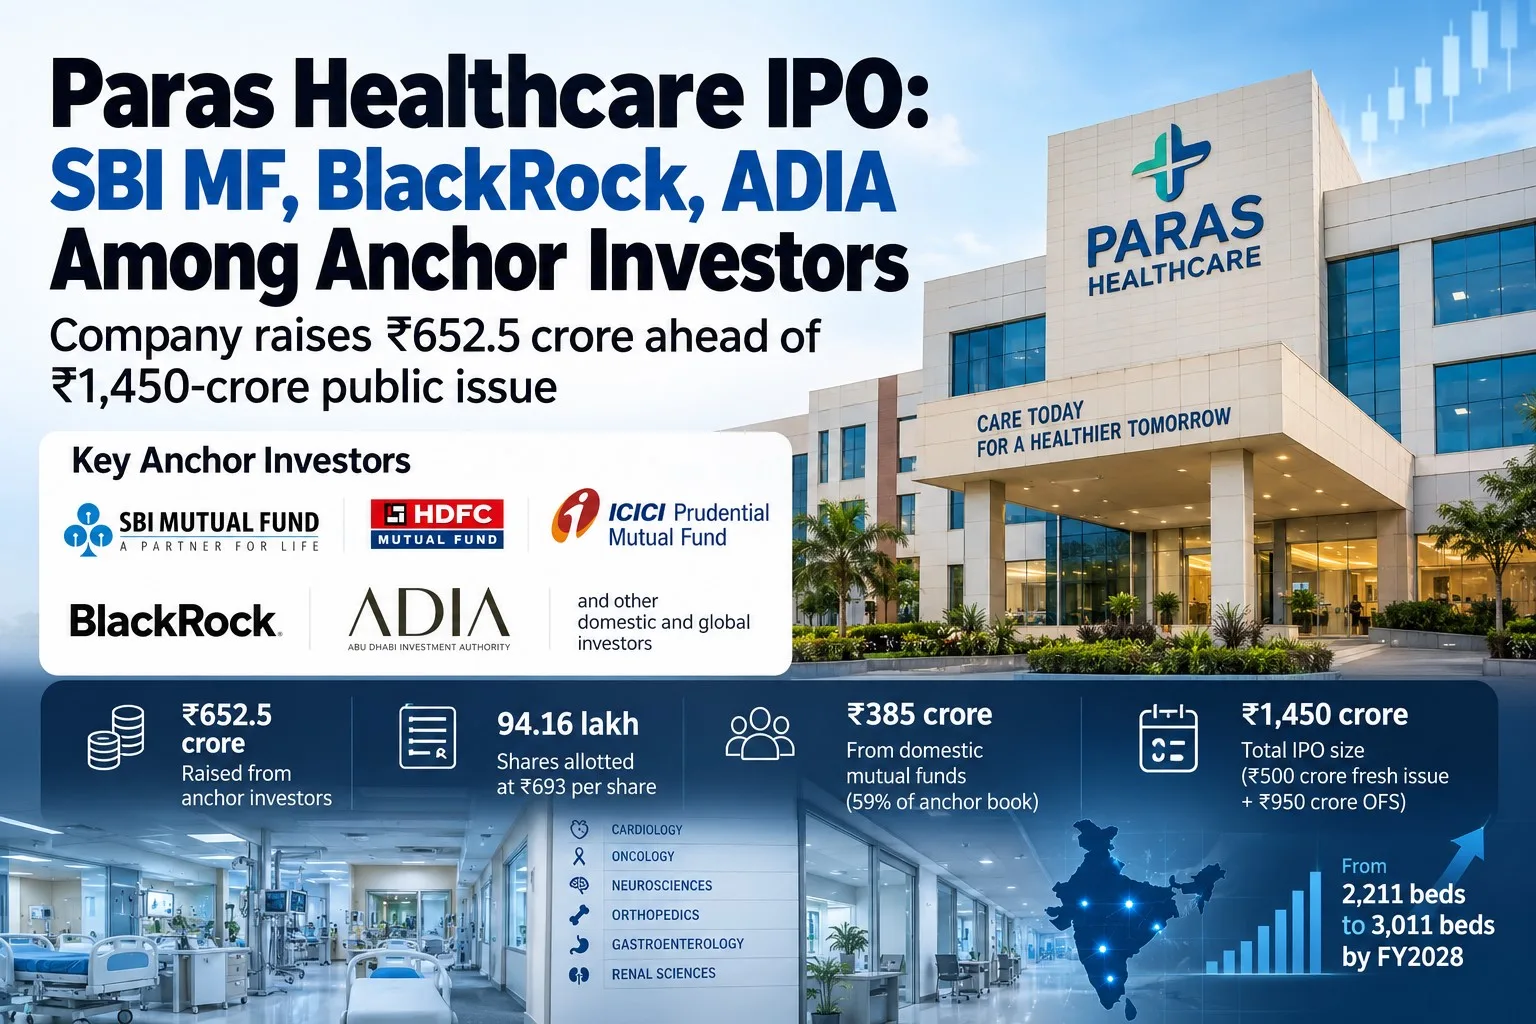
Paras Healthcare Limited has opened its ₹1,450-crore initial public offering (IPO) for subscription from October 21 to October 23, 2026. The hospital operator is entering the primary market after reporting a return to profitability in FY26, supported by stronger operating performance and rising revenue.
The IPO comprises a fresh issue of ₹500 crore and an offer for sale (OFS) of ₹950 crore. Shares are being offered in a price band of ₹660 to ₹693, valuing the company at approximately ₹7,498 crore at the upper end of the band.
Operating under the Paras Health brand, the company runs eight hospitals across North India, Bihar and Jharkhand. It plans to expand its bed capacity from 2,211 to 3,011 by March 2028, creating an opportunity to increase revenue as existing and newer facilities mature.
However, the investment case is not straightforward. Paras reported losses in FY24 and FY25 before returning to profitability in FY26. Its valuation is approximately 171 times FY26 post-issue earnings, making future profit growth particularly important.
The central question for investors is whether the company's expansion strategy can deliver sustainable earnings and cash flow at a pace that justifies the IPO price.
Paras Healthcare IPO: Key Details
Particulars | Details |
|---|---|
Company | Paras Healthcare Limited |
IPO opening date | October 21, 2026 |
IPO closing date | October 23, 2026 |
Price band | ₹660–₹693 per share |
Face value | ₹1 per share |
Total issue size | ₹1,450 crore |
Fresh issue | ₹500 crore |
Offer for sale | ₹950 crore |
Lot size | 21 shares |
Minimum investment at upper band | ₹14,553 |
Tentative allotment date | October 26, 2026 |
Tentative listing date | October 28, 2026 |
Proposed listing | BSE and NSE |
Book-running lead managers | JM Financial, BofA Securities India and Nuvama Wealth Management |
Registrar | MUFG Intime India |
The dates are tentative and may be revised. Investors should refer to the official offer documents for the final terms.
1. Understanding the IPO Structure: Fresh Issue Versus Offer for Sale
The ₹1,450-crore IPO consists of two components.
Component | Amount | Share of issue |
|---|---|---|
Fresh issue | ₹500 crore | 34.5% |
Offer for sale | ₹950 crore | 65.5% |
Total | ₹1,450 crore | 100% |
The distinction is important because the two components serve different purposes.
Fresh issue: Capital for debt reduction
The company intends to use the fresh issue proceeds primarily to reduce borrowings and support general corporate purposes. Approximately ₹357 crore is allocated to debt repayment at the parent company and its wholly owned subsidiary.
Reducing debt can lower interest costs, improve financial flexibility and help the company fund future investments from internal cash generation.
However, debt repayment alone does not guarantee a corresponding increase in shareholder returns. Investors should examine the remaining borrowings, lease liabilities, interest rates and future capital expenditure requirements.
Offer for sale: Proceeds go to existing shareholders
The ₹950-crore OFS represents shares sold by existing shareholders rather than newly issued shares.
The selling shareholders include promoter Dr. Dharminder Kumar Nagar and investor shareholder Commelina Limited.
The OFS proceeds go to the selling shareholders, not to the company's operating balance sheet. Therefore, the headline issue size should not be interpreted as ₹1,450 crore of fresh capital available for expansion.
A large OFS is not necessarily a negative signal. Investors should instead examine the reasons for the sale, the promoter's post-issue ownership and whether the company will have sufficient resources to execute its growth plans.
2. Paras Healthcare Business Model and Hospital Network
Paras Healthcare focuses on tertiary and quaternary healthcare services, including complex procedures that require specialist doctors, advanced medical equipment and multidisciplinary clinical teams.
Its network comprises eight operational hospitals with a combined capacity of 2,211 beds, serving markets across North India, Bihar and Jharkhand.
The company's key specialties include:
Cardiac sciences
Oncology
Neurosciences
Gastroenterology
Orthopaedics
Renal sciences
These high-acuity specialties contributed approximately 74.7% of FY26 revenue, according to IPO-related financial summaries.
Specialty-led healthcare can support higher revenue per patient than general hospital services. It can also strengthen referral networks and encourage patients to choose hospitals with established clinical expertise.
However, these services depend heavily on the availability and retention of experienced doctors, nurses and other clinical professionals. Competition for specialists can increase employee costs and affect hospital performance.
The company's regional strategy may offer opportunities to serve patients who otherwise travel to major metropolitan centres for advanced treatment. Its long-term success will depend on building strong clinical reputations, maintaining quality standards and achieving sufficient occupancy at each facility.
3. Financial Analysis: Revenue Growth and Profitability
Paras Healthcare's financial performance improved significantly in FY26 after two consecutive loss-making years.
Financial performance
Figures in ₹ crore, except EPS.
Financial metric | FY24 | FY25 | FY26 |
|---|---|---|---|
Revenue from operations | 1,129.04 | 1,294.06 | 1,605.95 |
EBITDA | 154.41 | 156.46 | 335.58 |
EBITDA margin | 13.68% | 12.09% | 20.90% |
Profit after tax | -15.33 | -57.98 | 43.83 |
EPS used in valuation | -1.57 | -5.94 | 4.05–4.34* |
EPS figures may differ according to the share-count basis used. The post-issue valuation calculation uses approximately ₹4.05 per share; investors should verify the exact diluted EPS and denominator in the RHP.
Revenue growth accelerated in FY26
Revenue increased from ₹1,129.04 crore in FY24 to ₹1,294.06 crore in FY25, representing growth of approximately 14.6%.
In FY26, revenue rose to ₹1,605.95 crore, an increase of approximately 24.1% year on year.
This acceleration is encouraging because a growing revenue base can help hospitals spread fixed costs across a larger volume of patient activity.
However, revenue growth alone is not sufficient to establish that a hospital business is creating value. Investors need to understand whether the increase came from existing hospitals, improving occupancy, higher revenue per occupied bed or newer facilities becoming operational.
EBITDA more than doubled in FY26
EBITDA increased from ₹156.46 crore in FY25 to ₹335.58 crore in FY26.
The EBITDA margin improved from approximately 12.1% to 20.9%, an increase of around 8.8 percentage points.
This is one of the most important developments in the company's financial performance.
A sustained improvement in operating margins could indicate better hospital utilisation, improved specialty mix, stronger cost control or maturation of recently expanded facilities.
Nevertheless, the magnitude of the increase warrants closer examination. Investors should determine whether the improvement is supported by recurring hospital operations and whether the company can maintain comparable margins while adding beds.
If margins normalise as expansion expenses rise, future earnings growth could be lower than the FY26 performance initially suggests.
Return to profitability
Paras Healthcare reported a net loss of ₹15.33 crore in FY24 and ₹57.98 crore in FY25 before recording a profit of ₹43.83 crore in FY26.
The return to profitability is positive, but the absolute profit remains relatively small compared with revenue and EBITDA.
FY26 net profit margin was approximately 2.73%.
This difference between operating earnings and net profit highlights the impact of depreciation, financing expenses and other costs associated with operating a capital-intensive hospital network.
For investors, the key question is whether the company can increase net profit consistently rather than relying solely on EBITDA growth.
4. Earnings Quality, Cash Flow and Debt
Hospital companies require substantial investment in buildings, medical equipment, technology and clinical infrastructure. As a result, EBITDA can provide useful information about operating performance, but it does not represent the cash available to shareholders.
Paras Healthcare reported FY26 operating cash flow of approximately ₹163.51 crore, compared with PAT of ₹43.83 crore.
Positive operating cash flow is encouraging, but investors should compare it with capital expenditure, lease payments, interest expenses and working-capital requirements.
A business can generate positive operating cash flow and still require external funding for expansion.
Debt remains an important consideration
The company's reported borrowings were approximately ₹854 crore, and the stated debt-to-equity ratio was approximately 2.16.
The fresh issue earmarks approximately ₹357 crore for repayment of borrowings across the parent company and its subsidiary.
This should improve the balance sheet if the repayment is completed as planned. However, investors must not assume that the company will become debt-free following the IPO.
Lease liabilities also matter because hospital operators may use leased properties rather than owning all their facilities. Rental commitments can remain substantial even after bank borrowings decline.
A comprehensive analysis should examine total borrowings, lease liabilities, available cash, interest coverage, debt maturities and the company's ability to fund expansion without excessive borrowing.
What investors should monitor
Three indicators will be particularly useful after listing:
Whether interest expenses decline following the planned debt repayment.
Whether operating cash flow continues to grow alongside EBITDA.
Whether capital expenditure and lease commitments remain manageable relative to earnings.
A sustainable improvement in all three would strengthen the long-term investment case.
5. Hospital Expansion: Growth Opportunity Through FY28
Paras Healthcare plans to increase its bed capacity from 2,211 to 3,011 by March 2028.
The planned increase of 800 beds represents capacity growth of approximately 36.2%.
The expansion includes an additional 300 beds in Gurugram and 500 beds in Ludhiana.
Additional capacity can increase revenue potential, particularly when new facilities are located in markets with strong demand for specialised treatment.
However, the financial returns from new beds depend on how quickly the facilities reach mature occupancy.
Hospitals need qualified doctors, nurses, diagnostic equipment, operating theatres and supporting infrastructure. These costs may arise before new facilities generate sufficient revenue.
The company must therefore balance growth with capital discipline.
Four indicators to watch
Bed occupancy: Rising occupancy indicates stronger utilisation, but the pace of improvement at individual hospitals matters more than the network average alone.
Average revenue per occupied bed: Growth can indicate a stronger specialty mix or increased revenue per patient. It should be assessed alongside patient volumes and affordability.
EBITDA per bed: This helps investors assess whether incremental capacity is generating adequate operating profit.
Return on invested capital: The returns generated by new hospitals should ultimately justify the capital invested in them.
If Paras can increase occupancy and EBITDA without significantly increasing financial leverage, expansion could create meaningful shareholder value. If occupancy takes longer to mature, returns may be delayed.
6. Paras Healthcare IPO Valuation: Is ₹693 Expensive?
At the upper price band of ₹693, the company is valued at approximately ₹7,498 crore after the IPO.
Using post-issue EPS of approximately ₹4.05, the implied price-to-earnings ratio is around 171 times.
The valuation is demanding, particularly because the company reported losses in FY24 and FY25 and only returned to profitability in FY26.
A high P/E ratio does not automatically mean that a stock is overpriced. Investors may be willing to pay a premium for businesses with strong growth prospects, improving returns and sustainable competitive advantages.
The challenge is determining whether Paras can deliver enough future earnings growth to justify the premium.
What does the valuation imply?
Using the stated post-issue market capitalisation of ₹7,498.34 crore, the following table illustrates the PAT required to support different P/E multiples.
Illustrative P/E multiple | Required annual PAT |
|---|---|
100 times | ₹75 crore |
75 times | ₹100 crore |
50 times | ₹150 crore |
These are mathematical illustrations, not fair-value estimates or earnings forecasts.
They show that the company's valuation would become more comfortable only if earnings grow substantially, the market continues to assign a premium multiple, or both.
Illustrative five-year earnings scenarios
Starting with FY26 PAT of ₹43.83 crore, the following scenarios show how different earnings growth rates would affect the valuation.
Scenario | Assumed annual PAT growth | Illustrative FY31 PAT | Current market cap / FY31 PAT |
|---|---|---|---|
Conservative | 10% | ₹70.5 crore | 106 times |
Base case | 20% | ₹109.0 crore | 69 times |
Optimistic | 30% | ₹162.8 crore | 46 times |
These scenarios assume five years of uninterrupted compounding, no additional equity dilution and no change in the current market capitalisation. They are not company guidance.
Even under the 20% growth scenario, the current market capitalisation would equal approximately 69 times the illustrative FY31 profit.
The implication is clear: investors are paying for future earnings rather than simply valuing the business on its latest reported profit.
Why EV/EBITDA is also important
The P/E ratio reflects equity value relative to net profit. For a capital-intensive hospital operator, enterprise value-to-EBITDA can provide a complementary perspective.
Enterprise value incorporates equity value and net debt, while EBITDA provides a measure of operating earnings before interest, taxes, depreciation and amortisation.
However, hospital comparisons require care because lease accounting, depreciation, acquisitions and the definition of adjusted EBITDA can materially affect reported multiples.
Investors should calculate Paras Healthcare's post-issue enterprise value using the actual debt and cash position and compare it with listed hospital operators using consistent financial definitions.
The valuation should also account for the capital required to build and mature additional hospitals.
7. Peer Comparison: Paras Healthcare Versus Established Hospital Operators
Paras Healthcare competes in a sector that includes Apollo Hospitals Enterprise, Fortis Healthcare and Max Healthcare Institute.
These businesses differ in scale, geographic reach, hospital maturity, specialty mix, capital structure and growth prospects. Their valuations should therefore be compared using consistent reporting periods and market prices.
Comparison factor | Paras Healthcare | Established listed hospital operators |
|---|---|---|
Operating footprint | Regional concentration in North and East India | Broader networks, with differences by company |
Earnings profile | FY26 return to profitability after losses | Varies by operator and reporting period |
Expansion stage | Significant planned capacity additions | Varies by operator |
Financial priority | Debt reduction and hospital expansion | Varies by operator |
Key valuation consideration | Sustainability of earnings recovery | Growth, mature hospital returns and capital allocation |
Paras may benefit from the maturation of newer facilities and the expansion of regional healthcare demand.
However, larger operators may have advantages in brand recognition, specialist recruitment, purchasing power, established referral networks and access to capital.
A meaningful peer valuation exercise should compare forward earnings growth, EV/EBITDA, net debt, return on invested capital and free cash flow rather than relying on headline P/E ratios alone.
8. Major Risk Factors Investors Should Understand
Risk 1: Sustainability of the FY26 turnaround
The company reported losses in FY24 and FY25 before returning to profitability in FY26. If operating margins decline or financing costs remain high, the improvement in net earnings may prove difficult to sustain.
Risk 2: High IPO valuation
At approximately 171 times post-issue FY26 earnings, the IPO price leaves substantial expectations for future growth. A slowdown in earnings or a reduction in the market valuation multiple could adversely affect share-price performance.
Risk 3: Expansion and capital requirements
New hospitals and additional beds require investment before they reach mature occupancy. Delays, higher costs or slower patient acquisition could reduce returns and increase funding needs.
Risk 4: Borrowings and lease obligations
Debt repayment will help, but the remaining borrowings, lease liabilities and future capital expenditure remain relevant. Excessive financial obligations could constrain expansion if cash flow weakens.
Risk 5: Dependence on clinical professionals
Hospitals depend on experienced doctors, nurses and other healthcare workers. Staff attrition can increase recruitment costs, disrupt clinical services and affect patient retention.
The offer documents disclose high employee attrition, making workforce retention a material operating issue to monitor.
Risk 6: Government schemes and institutional payers
Government health schemes and institutional arrangements can support patient volumes, but fixed reimbursement rates and longer collection cycles can pressure margins and working capital.
Investors should examine the proportion of revenue from these payers, outstanding receivables and collection trends.
Risk 7: Geographic and hospital-level concentration
A regional hospital network may be exposed to local competition and dependence on a limited number of key facilities. The contribution of individual hospitals to revenue and profitability should be assessed before assuming the entire network has uniform growth prospects.
9. IPO Subscription and Listing: What Should Investors Watch?
The issue is scheduled to close on October 23, 2026. The tentative allotment date is October 26, and the tentative listing date is October 28.
Investors should distinguish between subscription demand and fundamental value.
Strong subscription may indicate interest from institutional and individual investors, but it does not guarantee a profitable listing or attractive long-term returns.
Likewise, listing gains and long-term investment returns are different outcomes.
Before applying, investors should review the final issue terms, the latest subscription figures, the RHP risk disclosures and their own investment horizon.
The official IPO documents are available on the company's website under its investor and IPO documents section.
10. Paras Healthcare IPO: Who Should Consider It?
The IPO may interest investors who are comfortable analysing hospital businesses, can tolerate valuation risk and are willing to assess the company over a multi-year period.
The business case rests on several developments occurring together:
Continued revenue growth across existing hospitals.
Sustained improvement in EBITDA margins.
Higher occupancy at newer facilities.
Lower financing costs following debt repayment.
Stronger operating cash flow and returns on expansion capital.
Investors seeking companies with a long history of stable profitability may find the recent earnings turnaround less reassuring.
Similarly, investors focused on valuation discipline should carefully consider whether the expected earnings growth compensates for the premium being paid.
The suitability of the IPO ultimately depends on an investor's risk tolerance, time horizon, portfolio concentration and valuation expectations.
Conclusion: A Promising Hospital Growth Story at a Demanding Price
Paras Healthcare's IPO combines a growing regional hospital network, accelerating revenue, a sharp improvement in EBITDA and a plan to expand bed capacity by approximately 36% by FY28.
The planned debt repayment is another positive because it could reduce interest costs and improve financial flexibility.
However, the company's return to profitability is recent, its net profit remains modest relative to revenue, and its expansion programme will require careful execution.
At an implied post-issue P/E of approximately 171 times FY26 earnings, the IPO valuation places considerable importance on future growth.
For the investment case to strengthen, Paras must demonstrate that FY26's margin improvement is sustainable, new beds generate adequate returns and operating cash flow grows alongside earnings.
Disclaimer: This article is for educational and informational purposes only and does not constitute investment advice or a recommendation to apply for the IPO. IPO investments carry market risk, including the possibility of losing capital. Investors should read the complete Red Herring Prospectus and consult a SEBI-registered investment adviser where appropriate.
Editorial source note: Financial figures and issue details should be cross-checked against the final RHP and official exchange disclosures before publication. IPO terms, dates and subscription figures may change.